
What Counts as a Day in Mobility Compliance?
September 23, 2026
“What is a day?” may sound like a stupid question, but in mobility compliance it is an important consideration.
Counting “days” is important for mobility compliance as days are important for:
- Determining whether a business traveler is under a de minimis number of days, such as the 183-day limit referenced in most double tax treaties.
- Calculating the percentage of sourcing income when using a ‘grant-to-vest’ or grant-to-exercise’ sourcing methodology. For more information on these methodologies, see “How to Source Equity Comp Income for Mobile Employees.”
- For some jurisdictions, the number of days spent in a jurisdiction can determine residency. While we address this further below from the perspective of counting days, because an individual’s residency status can be impacted by personal circumstances such as location of family, availability of permanent housing, etc., we generally recommend that the determination of residency be made by the individual and/or their tax advisors.
However, there is no single global definition of what constitutes a day for the purposes of mobility compliance. Jurisdictions determine days in several different ways, below are some examples.
Any Portion of a Day Counts as a Day
For federal income tax, the United States uses the substantial presence test to determine residency:
- Count all days present in the current year
- Add one-third of days from the previous year
- Add one-sixth of days from the year before that
If the total equals 183 or more days, the individual is considered a U.S. resident for federal tax purposes. Many US states use other criteria to determine residency.
The IRS treats any part of a day as a full day for the purposes of the substantial presence test with some limited exceptions.
Any Portion of a Workday Counts as a Workday
This is a slight variation on the above, whereas the substantial presence test considers days of presence, this methodology only counts workdays. For example, in relation to the application of the 14-day de minimis for non-resident business travel, New York, Technical Memorandum TSB- M-12 states
When applying the 14-day rule, any part of a day spent working in New York counts as a full day.
Split Travel Days
A recent Dutch Supreme Court ruling ruled that for the determination of international working days in the context of relief from double taxation, it is not necessary to calculate only with whole days. In the case of international business trips, in order to ensure ease of applicability, half of the travel day must be attributed to the country of departure and half to the country of arrival.
Ability to Prorate Using Portions of Days
The US federal sourcing provisions for non-US residents consider the portion of time spent in the country rather than the number of days. Treasury Reg 26 CFR § 1.861-4(b)(F) states:
( F) Time basis. The amount of compensation for labor or personal services performed within the United States determined on a time basis is the amount that bears the same relation to the individual's total compensation as the number of days of performance of the labor or personal services by the individual within the United States bears to his or her total number of days of performance of labor or personal services. A unit of time less than a day may be appropriate for purposes of this calculation. …..
This allows the employer to allocate income based on periods less than a day, if appropriate.
Practical Tips
Most jurisdictions do not define the term “day” for mobility compliance purposes. So what should companies that do not have the resources to review and apply disparate legislative guidance do? A few practical tips would make life easier:
- Determine a policy on how the company will define “day” for each purpose.
- Determine how travel days will be allocated—to origin, to destination, split between the two.
- Determine whether to use calendar days or workdays. It is customary to use:
- Calendar days for transfers. For example, someone who transfers on June 30 will be deemed to work in one location from January 1 to June 30 and the next location from July 1 to December 31.
- Workdays for hybrid employees or business travelers. For example, three days spent working in California.
- When using workdays, establish a policy for the number of workdays in a year. This is usually dictated by HR or payroll policy. When I began my career, it was common to use 240 workdays a year (365 calendar days, multiplied by five workdays over seven calendar days less four weeks of vacation time). However, I am now seeing companies use 260 as a standard. The number of annual workdays may vary by job role or position.
Document the above and use consistently.
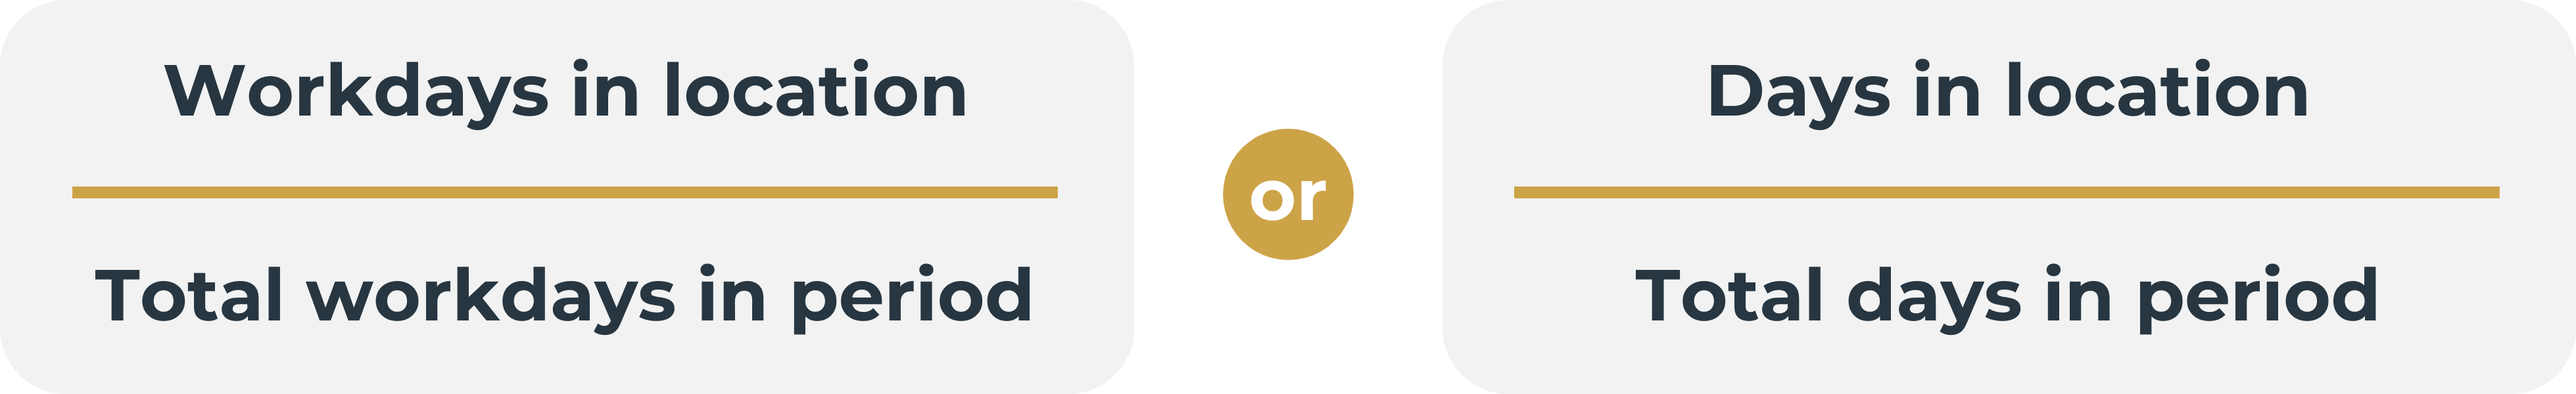
Finally, when calculating sourced income, ensure that the same determination is used in the numerator as in the denominator, i.e.,
As individual laws vary by jurisdiction, a tax inspector may disagree with the policy, However, as is usually the case for mobility compliance, it is more defensible to have a thought-out policy that is customized to your company’s situation and apply it consistently than a haphazard application of the rules.
-
By Marlene ZobayanPartner
Rutlen Associates LLC
Marlene Zobayan is a partner at Rutlen Associates LLC, a boutique consulting firm helping companies with their global equity plans and/or mobile employees.